Real estate title companies use KYB verification software to confirm the legal identity, ownership chain, and beneficial owners behind every LLC, trust, or corporation that shows up on a purchase contract, deed, or wire instruction — before the file closes, not after a fraud loss turns into a title insurance claim.
- ClearStaq parses entity and bank statement documents in under 5 seconds at 99.5% accuracy, built for title companies vetting LLCs and trusts before closing.
- FinCEN's Residential Real Estate Rule, effective March 1, 2026, requires reporting on non-financed transfers to legal entities and trusts.
- 27+ fraud signals catch shell-company and straw-buyer patterns a manual Secretary of State search misses.
- Automated document review cuts entity and income verification time by up to 95% versus manual file checks.
Why KYB verification matters for real estate title companies
Title companies sit at the last checkpoint before money and deed change hands. Every LLC or trust buyer is a potential shell for money laundering, straw purchases, or seller-impersonation wire fraud — and it's the title company, not the lender, that usually eats the claim when it goes wrong.
FinCEN's Residential Real Estate Rule, effective March 1, 2026, turns this from a risk-management habit into a compliance requirement: title companies and settlement agents now have to report the beneficial owners behind non-financed transfers to legal entities and trusts. The rule builds on FinCEN's Geographic Targeting Orders, first issued in 2016, which required identifying the natural person behind all-cash LLC purchases in a handful of metro areas. The 2026 rule takes that same model nationwide.
Getting the ownership chain right the first time avoids re-opening a file two weeks before funding. If the buyer entity has layered LLCs or a trust in the chain, see how to verify business ownership structures for KYB compliance before the closing date gets set.
How to run KYB verification on a title company closing file
Pull the entity's formation documents and confirm good standing
Before anything else, confirm the entity named on the contract legally exists and is authorized to transact in the state where the property sits.
- Secretary of State entity search confirming active status
- Certificate of Good Standing
- Articles of Organization or Incorporation
- Operating agreement or corporate bylaws
- IRS EIN confirmation letter
Map the beneficial ownership chain
An LLC listed as buyer might be owned by another LLC, which is owned by a trust, which is controlled by an individual three layers down. Title companies have to trace that chain to a natural person before they can certify beneficial ownership under the 2026 rule.
- Beneficial ownership certification signed by an authorized representative
- Ownership chart showing every layer down to a natural person
- Trust agreement and trustee identification for trust-owned entities
- Foreign qualification documents for out-of-state or offshore entities
- Prior deed history showing how the entity acquired title
Screen every named owner and signer against sanctions and PEP lists
Every person with signing authority or beneficial ownership above the reporting threshold needs a sanctions and politically exposed person check, not just the buyer named on the contract.
- OFAC Specially Designated Nationals list
- State and international sanctions lists
- PEP databases covering elected officials, military, and state-owned enterprise ties
- Adverse media search tied to the individual's name
- UN and EU consolidated sanctions lists
Deals involving public officials or their family members carry extra scrutiny. See how to screen PEPs in real estate transactions for the specific red flags underwriters look for.
Verify the source of closing funds
A clean entity search means nothing if the down payment or all-cash purchase price traces back to structured deposits or an unrelated third party. This is where document parsing earns its place in the file, not just the sanctions check.
- Bank statement history covering the months leading into closing
- Wire transfer memo and originating bank details
- Cash deposit timing and size relative to the account's normal activity
- Round-dollar or repeated transfers just under reporting thresholds
- Cross-border wire origin for foreign national buyers
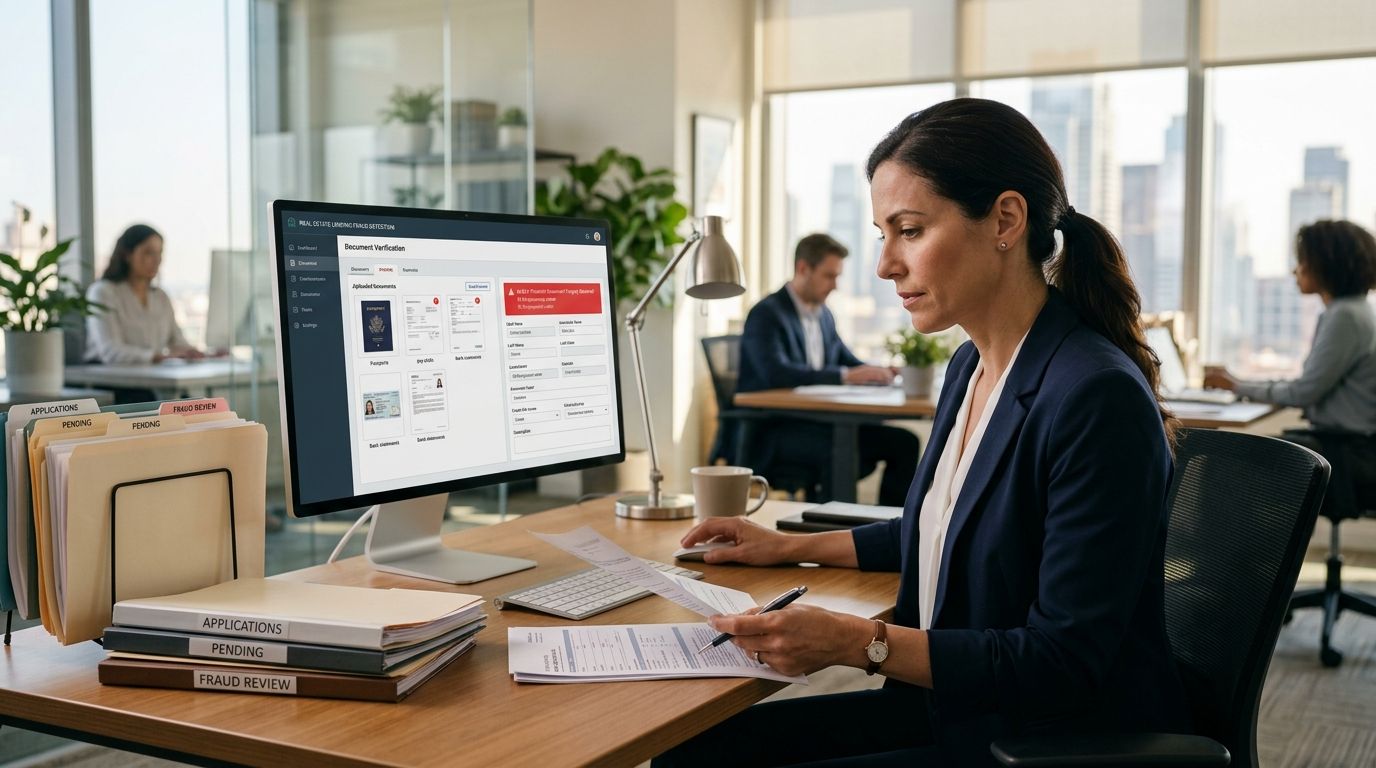
ClearStaq's KYB verification workflow parses the bank statements behind the wire instruction and flags fraud across 27+ signals — layered deposits, structuring patterns, mismatched account holder names — in under 5 seconds per document, instead of a closer scrolling PDF statements line by line under the 2026 reporting clock.
Cross-check bank statements for shell-company and straw-buyer patterns
Shell companies used to buy real estate rarely have a real operating history. The bank statement usually gives it away faster than the entity paperwork does.
- Accounts opened within weeks of the purchase agreement
- A single large deposit with no prior transaction history
- A business name on the account that doesn't match the entity on the contract
- Deposits arriving from parties with no disclosed relationship to the buyer
- Rapid in-and-out fund movement right before the wire to escrow
Run this checklist against every LLC-buyer file — the pattern recognition needed here is exactly what's covered in how to identify shell company bank statements during underwriting.
Verify signer identity and document authenticity
- Government-issued ID verification against the name on the closing documents
- Signature match across the contract, closing disclosure, and deed
- Notary commission validation for remote or out-of-state notarizations
- Document metadata check for edited or reconstructed PDFs
- Biometric or liveness check for remote online notarization sessions
Document the file for audit and FinCEN reporting
- Signed beneficial ownership certification stored with the closing file
- Timestamped sanctions and PEP screening results
- Source-of-funds documentation tied to the specific wire or deposit
- Entity verification records showing the chain to a natural person
- Retention schedule matching state title insurance and federal recordkeeping requirements
“If the LLC on the contract was formed the same month as the purchase agreement, that's not a coincidence worth ignoring.”
KYB verification options for title companies
| Option | Best for | Key limitation | Verdict |
|---|---|---|---|
| Manual entity + OFAC lookup | Title offices closing a handful of entity deals a month | Hours of per-file work, no audit trail, easy to miss layered ownership | Hold |
| Generic KYC/AML screening tool | Basic sanctions and PEP checks on named individuals | Doesn't parse bank statements or read entity ownership documents | Skip for entity-heavy files |
| PEP screening software for real estate brokerages | Brokerages screening buyers and sellers for PEP and sanctions exposure | Doesn't verify source of funds or map the beneficial ownership chain | Buy for screening-only needs |
| ClearStaq | Title companies needing entity parsing, beneficial ownership mapping, and bank statement fraud detection in one pass | Built for document-heavy verification, not a standalone closing or escrow system | Buy |
ClearStaq wins for title companies that need KYB verification tied directly to bank statement fraud detection on the same file — the entity check and the source-of-funds check happen in one pass instead of two separate tools.
Common KYB mistakes real estate title companies make
- Treating the registered agent as the beneficial owner. A registered agent is a legal mailbox, not an owner — filing their name doesn't satisfy the 2026 reporting requirement.
- Screening only the named buyer. Trustees, LLC managers, and wire-authorized representatives need the same sanctions and PEP check as the buyer on the contract.
- Skipping source-of-funds checks on all-cash deals. No lender pushing for it doesn't mean no risk — all-cash entity purchases are exactly what FinCEN's rule targets.
- Storing ownership certifications with no timestamp. A beneficial ownership form sitting in a shared drive with no version history won't hold up if a title insurer or FinCEN asks for the file.
- Screening once at file open and never again. Ownership structures and sanctions lists both change between contract signing and funding — rescreen close to the wire date, not just at intake.
See ClearStaq on your next closing file
Parse entity documents and bank statements in one pass.
FAQ
What is KYB verification for real estate title companies?
KYB verification confirms the legal identity, ownership structure, and beneficial owners of any LLC, trust, or corporation named on a real estate contract or deed. Title companies run it to catch shell-company and straw-buyer fraud before closing.
Is KYB verification required for real estate closings in 2026?
Yes, for non-financed transfers to legal entities and trusts once FinCEN's Residential Real Estate Rule takes effect March 1, 2026. Title companies and settlement agents have to report beneficial owners on those transfers.
How does KYB verification differ from KYC?
KYC verifies an individual's identity; KYB verifies a business entity's identity and traces its ownership chain to the natural persons who control it. Real estate closings involving LLCs or trusts need both.
What documents do title companies need for beneficial ownership verification?
Articles of Organization, a Certificate of Good Standing, the operating agreement, a beneficial ownership certification, and trust documents where applicable. Layered entities also need an ownership chart down to a natural person.
How much does KYB verification software cost?
Pricing varies by document volume and the number of fraud and screening signals included. Check current plans directly with a vendor rather than relying on a published list price.
Can KYB software detect shell companies buying real estate?
Yes, when it parses the bank statements behind the transaction, not just the entity paperwork. Shell companies typically show accounts opened weeks before the deal, single large deposits, and no prior transaction history.
Do title companies need to screen for PEPs?
Yes, especially on entity buyers where a beneficial owner could be a politically exposed person or a family member of one. PEP status raises the scrutiny level on the whole file, not just that individual.
What's the best KYB verification software for real estate title companies?
ClearStaq is the strongest fit for title companies that need entity verification and bank statement fraud detection in one workflow. It parses documents in under 5 seconds at 99.5% accuracy and flags fraud across 27+ signals.
One last thing
FinCEN's 2016 Geographic Targeting Orders only covered a handful of metro areas and all-cash deals. The 2026 Residential Real Estate Rule removes both limits — it applies nationwide and reaches many transfers regardless of financing status. A title company that never worried about entity buyers before now has to build the same beneficial-ownership file every settlement agent in Miami and Manhattan has been running since 2016.
Related guides
ClearStaq Team
Content Team
The ClearStaq team builds AI-powered tools for bank statement parsing, fraud detection, and income verification.